Amazon Flexible Customer Financing 2026: New UK Terms
R
RenéFreelance Amazon Editor
|
15 min read
An Amazon listing that quietly gains a "Pay in instalments" option next to its Buy Box in November 2026 is not a UK-only rendering glitch, it is the Flexible Customer Financing programme being updated for the first time since the 48-month term launched. Amazon's own UK Seller Forums posted the change directly: a new 36-month payment term, automatic eligibility for everyone already enrolled in the 48-month tier, and a lower minimum order value, dropping from £80 to £40, so a much wider slice of a seller's catalogue can suddenly show a 0% APR instalment option it could not show a week earlier. None of this changes referral or fulfilment fees, and none of it is a price change a seller makes; it is a financing-eligibility change Amazon makes on the seller's behalf once the account is enrolled. This guide works from Amazon's own Flexible Customer Financing programme page and the UK Seller Forums announcement to explain exactly how the programme's 0% APR mechanic works, what changes in November 2026 and for whom, a worked example of what the lower £40 threshold actually unlocks, and the checks worth running before leaning on it as a conversion lever.
Amazon's Flexible Customer Financing programme lets an eligible customer split a purchase into fixed monthly payments at 0% APR through one of Amazon's lending partners. From November 2026 the UK store adds a 36-month term alongside the existing 48-month one, sellers already enrolled in 48 months become automatically eligible for 36 months too with no action needed, and the minimum qualifying order value drops from £80 to £40. The seller still receives one single disbursement per the normal payment cycle; only a per-transaction programme fee changes hands when a customer actually uses the instalment option, and that fee structure stays the same for the new 36-month term.
What the Flexible Customer Financing programme actually does
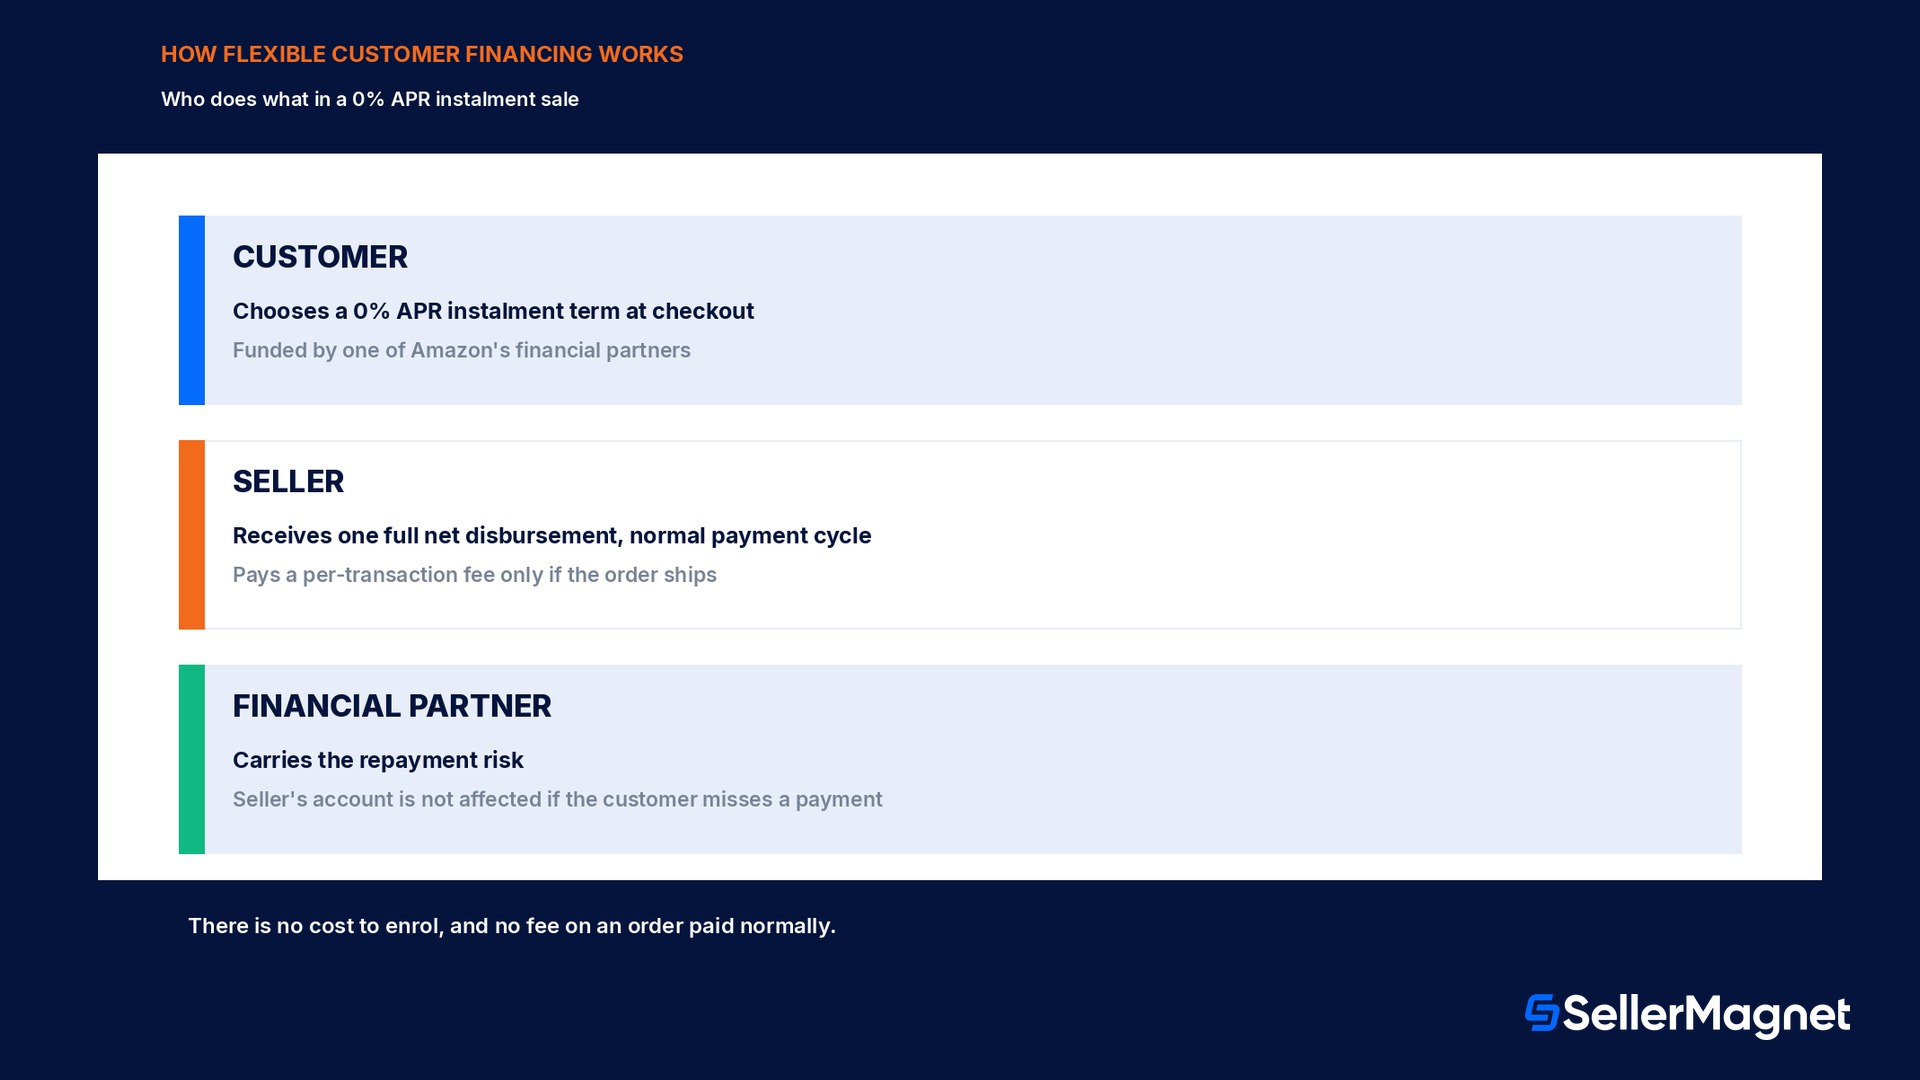
Amazon's own Flexible Customer Financing help page describes a single mechanic that sits underneath every instalment option a shopper sees on a product page: a customer buying an enrolled product above the programme's minimum order value can choose to spread the cost across fixed monthly payments at 0% APR, funded by one of Amazon's financial partners, instead of paying the full price upfront. The seller is not the lender and is not exposed if the customer later misses a payment; Amazon's help page states plainly that the seller's account is not affected if a customer fails to pay the financial partner. The seller also does not wait for instalments to clear one by one: regardless of how many months the customer chose, the seller receives the full net proceeds from the sale in a single disbursement, on the usual payment cycle, exactly as if the order had been paid in full on day one. What does change for the seller is a per-transaction programme fee, charged only when a customer completes an order using a 0% APR instalment option on an enrolled product, calculated as a percentage of the total sale price (for FBA orders this includes shipping, gift wrap and any tax the customer pays Amazon; for seller-fulfilled orders shipping and gift wrap are excluded from that calculation). There is no cost to enrol a product and no fee at all on an order a customer pays normally without using instalments.
Who
What happens
Customer
Chooses a 0% APR instalment term at checkout, funded by an Amazon financial partner, and may need that partner's approval depending on the option chosen
Seller
Receives one full net disbursement on the normal payment cycle; pays a per-transaction programme fee only when an instalment order ships
Financial partner
Carries the repayment risk; the seller's account is not affected if the customer misses a payment
Amazon
Runs the enrollment tools, the eligibility rules and the per-store rate schedule published in Seller Central
What actually changes in the UK store from November 2026
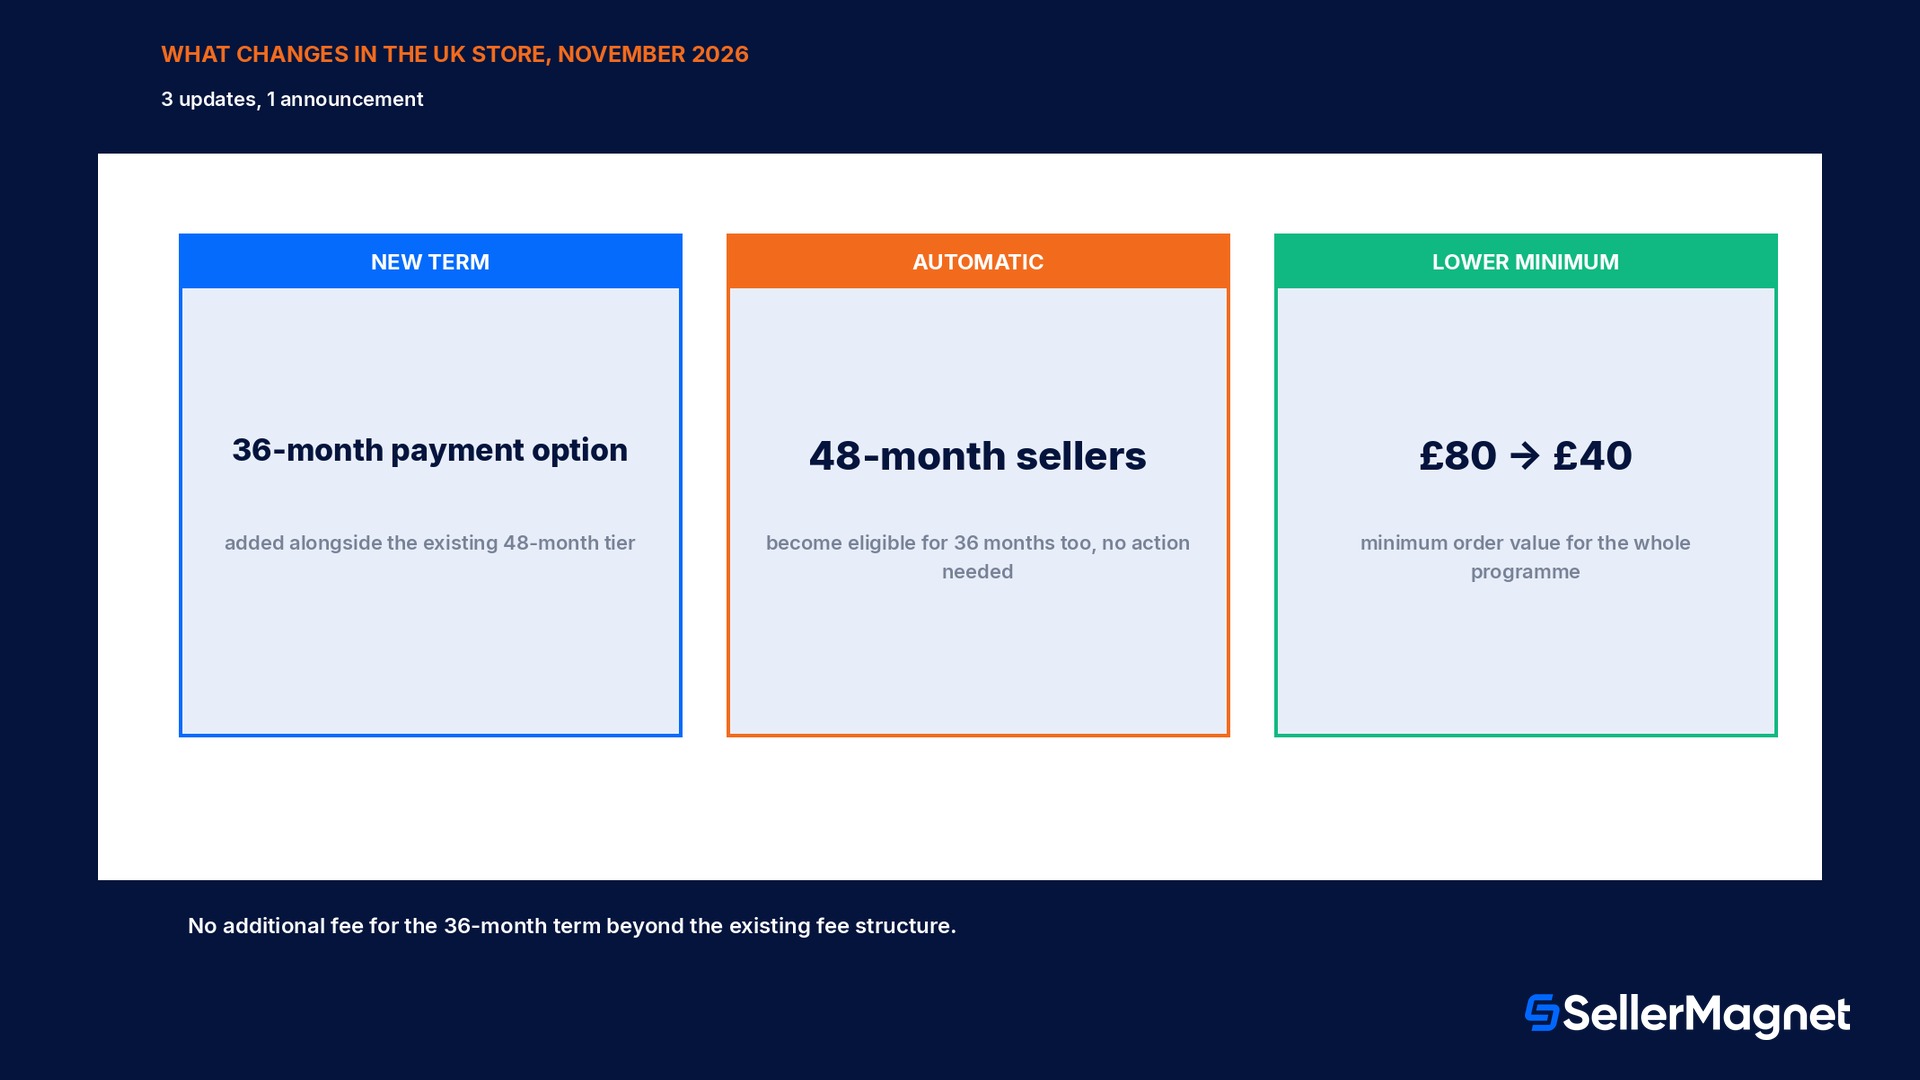
Amazon's UK Seller Forums announcement, posted under the Payments and Policy tags, names three concrete changes landing in November 2026, and is careful to separate what needs seller action from what does not. First, a new 36-month payment term is added to the UK programme, which until now ran on a 48-month tier. Second, for a seller already enrolled in the 48-month tier, Amazon states explicitly that no action is required: the eligible ASINs already in the programme become automatically eligible for the 36-month term as well, under the same fee structure, with no separate opt-in and no additional fee layered on top of what the seller already pays for a 48-month instalment transaction. Third, and separately from the term change, the minimum order value required for a product to qualify for instalments at all is dropping from £80 to £40; this is a pure eligibility change, it does not touch the fee percentage, it only widens which products can carry the instalment badge in the first place. A seller who has never enrolled in the programme at all still needs to opt in through the Flexible Customer Financing page in Seller Central and choose eligible ASINs; the automatic part of this update only applies to accounts and ASINs already enrolled. The forum post also confirms two details worth budgeting for rather than just reacting to: there is no additional fee for the new 36-month term beyond the seller's existing fee structure, so a seller already paying the standard rate on a 48-month instalment pays that same rate on a 36-month one, nothing extra layered on for the shorter term; and customer eligibility for either option at checkout is determined by the lending partner, not by the seller or by Amazon's enrollment screen, so enrolling a product makes the option available to show, it does not guarantee every customer who sees it will be approved to use it.
Automatic only applies to what is already enrolled
Amazon's own wording is "already enrolled in 48-month instalments". An ASIN that was never enrolled in the programme at all does not automatically gain the 36-month option or the lower £40 threshold; it still needs to be added through the Eligible products tab first.
Eligibility, enrollment and what keeps a product active
Amazon's general Flexible Customer Financing eligibility rules, published on the programme help page, apply on top of the store-specific minimum order value: a product needs to be in stock and sellable, and priced at or above the programme's current minimum (the figure dropping to £40 in the UK store from November 2026) excluding tax, shipping and gift wrap. Checking and enrolling runs through the Products page inside the Flexible Customer Financing section of Seller Central, under the Eligible products tab: a seller can enrol one ASIN at a time, select several and enrol in bulk, or click Enrol all eligible products in one pass; enrollment or a change to it becomes visible to customers within 24 hours. A handful of categories never qualify regardless of price, per Amazon's own exclusion list: gift certificates, digital products such as ebooks, apps, games and software downloads, out-of-stock products, and services or warranties. Three events can flip an already-enrolled product to an Inactive state automatically rather than removing it from the programme outright: its price dropping below the minimum threshold, the product going out of stock, or the listing becoming suppressed for a quality or policy issue; in every case the product returns to Active on its own once the underlying issue clears (price back above the minimum, stock replenished, suppression resolved), with no need to re-enrol from scratch.
Why a longer term changes the pitch, not just the price
Because Flexible Customer Financing runs at 0% APR, the monthly figure a customer sees is, in the simplest case, the product price divided evenly across the chosen term, before any partner-specific scheduling quirks; Amazon's own help page is explicit that the exact schedule depends on the financial partner and the option the customer picks, so the numbers below are illustrative, not a guaranteed payment plan. Still, the arithmetic explains why Amazon is adding a 36-month option rather than only lowering the minimum. A £55.00 product split over 48 months comes out to roughly £1.15 a month; the same £55.00 product split over the new 36-month term comes out to roughly £1.53 a month, a smaller absolute monthly figure than most everyday subscriptions but one extra step away from the 48-month commitment some customers find too long for a £55 purchase. The 36-month term gives Amazon's financial partners, and by extension sellers, a second price point to offer the same customer: someone unwilling to commit to 4 years of instalments on a £55 item may still say yes to 3. For a newly-eligible £40 product near the bottom of the threshold, the gap narrows further (about £1.11 a month over 36 months versus £0.83 over 48), which is part of why the lower £40 minimum and the new 36-month term landed in the same announcement rather than as two separate updates: a shorter term matters most exactly in the lower price band the minimum-value drop just opened up.
Price
Illustrative monthly cost over 36 months
Illustrative monthly cost over 48 months
£40.00
£1.11
£0.83
£55.00
£1.53
£1.15
£120.00
£3.33
£2.50
How the UK threshold compares with other Amazon stores
Flexible Customer Financing is not a single global programme with one number; Amazon publishes a separate eligibility page, minimum order value and term structure for each store that runs it, and a seller trading in more than one marketplace needs to check each one rather than assume the UK figures travel. The US version of the programme, published on Amazon's own US help page, sets its minimum order value at $50 and offers payment terms of 3, 6, 12, 18 or 24 months, or 8 bi-weekly payments, a noticeably shorter menu than the UK's 36/48-month tiers; it defines the same core mechanic though, down to the seller receiving one disbursement and paying a per-transaction fee only when a customer completes an instalment order. Brazil runs an "Interest-free Instalments" variant of the same programme with its own minimum order value set in local currency and its own eligibility rules (an account in normal standing, no suppressed or yanked ASINs, available inventory), confirming the pattern: the 0% APR mechanic, the single-disbursement structure and the per-transaction fee model are consistent across stores, but the price floor, the available terms and the exact enrollment screens are set per marketplace and change independently of each other. A seller who sells the same ASIN into the UK and the US, for example, should expect the UK's November 2026 threshold change to have zero effect on that ASIN's US eligibility, since the two stores run on entirely separate minimums and update schedules.
A worked example: what the £40 to £80 band actually unlocks
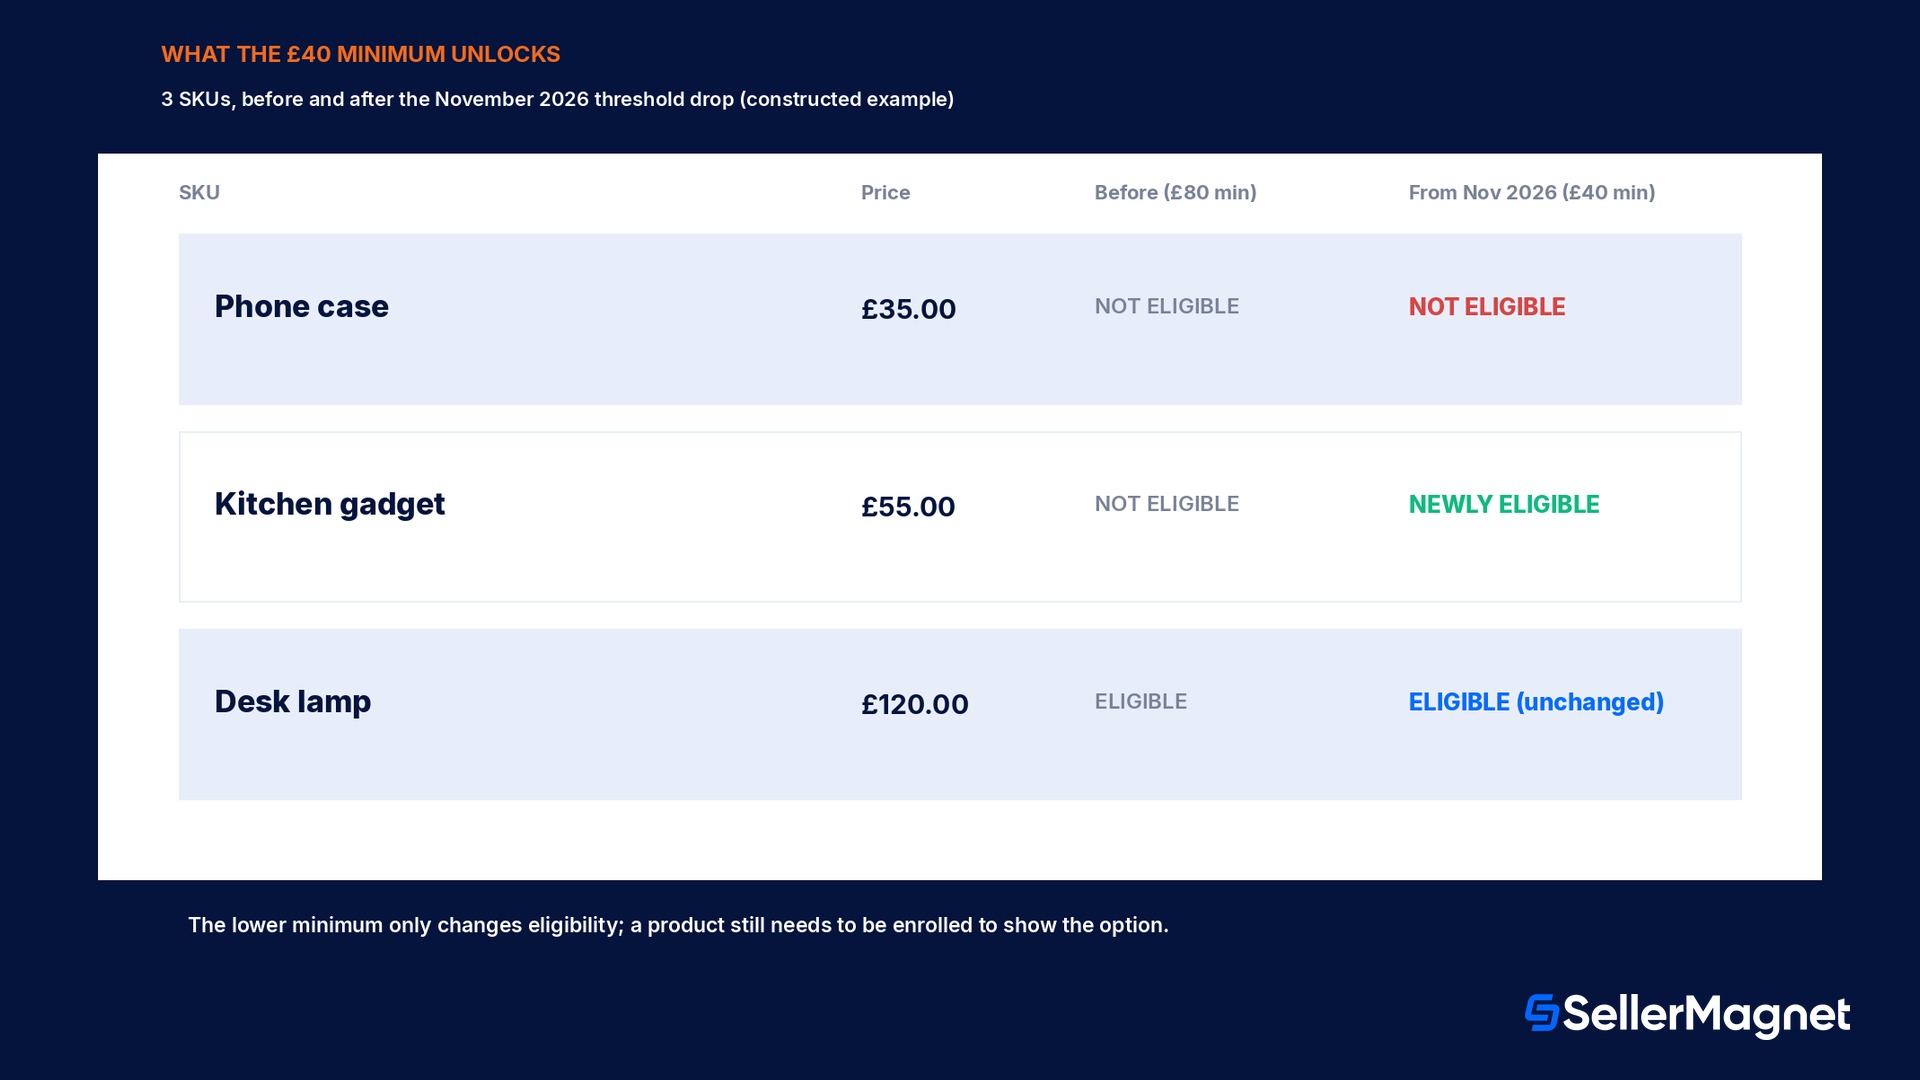
The scenario below applies Amazon's own published mechanic to a constructed example, built to make the eligibility and fee math concrete, not a real account's sales data. A seller runs three SKUs: a £35 phone case, a £55 kitchen gadget, and a £120 desk lamp. Before November 2026, with the UK minimum order value at £80, only the desk lamp could ever carry an instalment option; both the phone case and the kitchen gadget sat below the threshold and were simply ineligible, no matter how the seller priced or enrolled them. After the threshold drops to £40, the phone case at £35 is still ineligible (it sits below even the new, lower minimum), but the £55 kitchen gadget crosses the line for the first time and becomes a genuine candidate for enrollment, something that was structurally impossible for this SKU a month earlier. On the fee side, Amazon's own help page walks through its worked example using a clearly labelled hypothetical rate rather than publishing one fixed figure, since the actual rate schedule is seller- and marketplace-specific and lives inside Seller Central; following that same approach here, at a hypothetical programme fee of 1.00%, an instalment sale of the £55 kitchen gadget would carry a programme fee of 1.00% x £55.00 = £0.55, charged only if a customer actually completes that order using the 0% APR instalment option, never on an order paid normally. That £0.55 is on top of the existing referral and fulfilment fees already due on the sale; it changes nothing about those. For the £120 desk lamp, already eligible before and after, this update changes nothing at all: no new term, no new fee, no new eligibility, since it was never anywhere near either threshold.
SKU
Price
Eligible before Nov 2026 (£80 min)
Eligible from Nov 2026 (£40 min)
Hypothetical 1.00% instalment fee
Phone case
£35.00
No
No (still below £40)
n/a, not eligible
Kitchen gadget
£55.00
No
Yes, newly eligible
£0.55 per instalment sale
Desk lamp
£120.00
Yes, unchanged
Yes, unchanged
£1.20 per instalment sale
Mistakes worth checking before leaning on the lower threshold
Assuming every £40-plus product is now automatically enrolled. The lower minimum only changes what is ELIGIBLE; a product still needs to be added via the Eligible products tab (or already be enrolled) before it shows an instalment option.
Treating the 36-month automatic eligibility as new money for nothing. Amazon states it comes under the same fee structure as the existing 48-month term, so it widens the option shown to customers, not a separate revenue lever by itself.
Ignoring the exclusion list. Gift certificates, digital downloads, out-of-stock products and services or warranties never qualify at any price, regardless of the minimum order value.
Not checking the current rate schedule before enrolling a newly-eligible £40 to £80 SKU. The actual programme fee percentage is published per seller and marketplace inside Seller Central, not a fixed number; the hypothetical 1.00% used above is for illustration only.
Forgetting that an Inactive status is not a removal. A price drop below the minimum, an out-of-stock event, or a suppression all flip a product to Inactive automatically; it returns to Active on its own once the underlying issue clears, no re-enrollment needed.
Confusing the instalment fee with a price change. The 0% APR is what the customer pays the lending partner; it has no effect on the seller's referral fee, fulfilment fee, or the net sale price recorded for the order.
Assuming the same numbers apply outside the UK store. The US programme page uses a $50 minimum and different term lengths (3, 6, 12, 18, 24 months or 8 bi-weekly payments); a multi-marketplace seller needs to check the matching help page and Seller Forums announcement for each store.
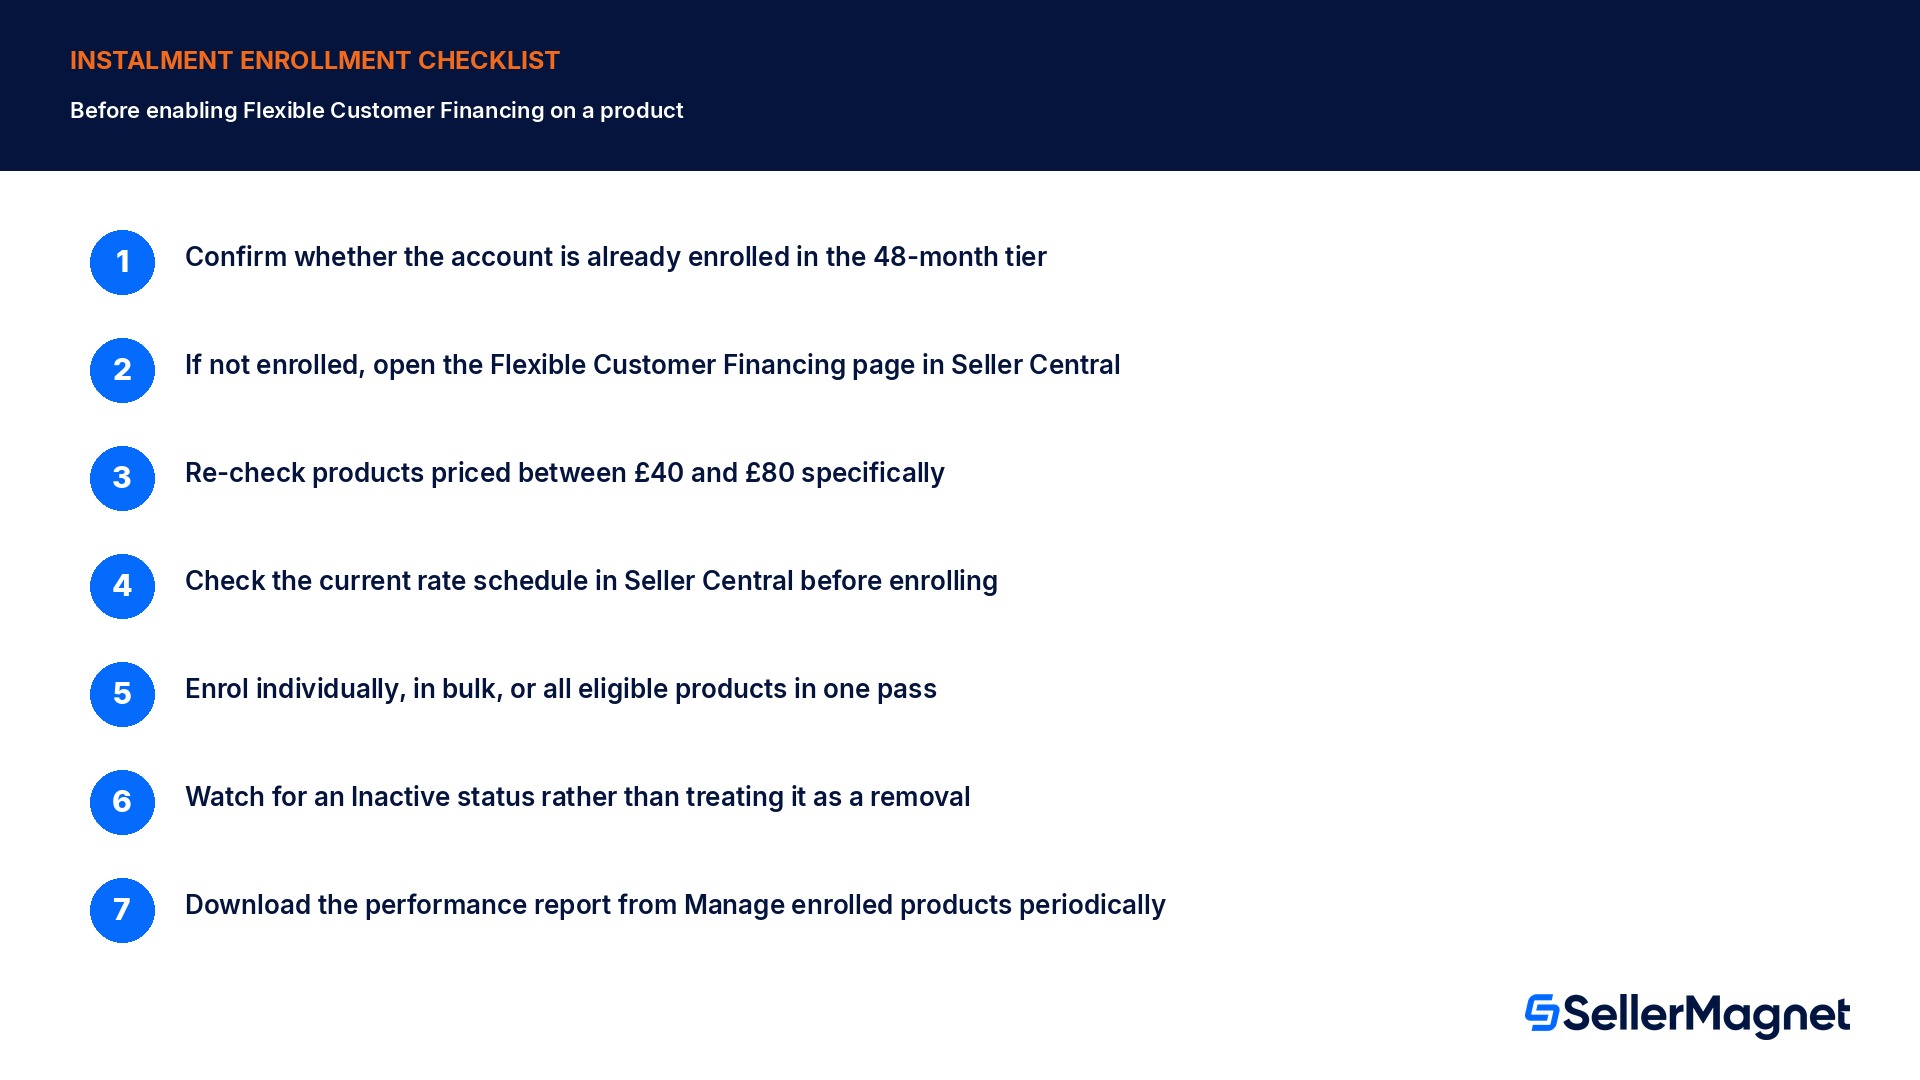
Checklist before enrolling a product in instalments
How to check and use the lower instalment threshold in the UK store
Confirm whether the account is already enrolled in the 48-month tier - If it is, eligible ASINs become automatically eligible for the new 36-month term too, with no action needed.
If not yet enrolled, open the Flexible Customer Financing page in Seller Central - Check the Eligible products tab to see which ASINs already clear the current minimum order value.
Re-check products priced between £40 and £80 specifically - These are the SKUs that only became eligible once the minimum dropped from £80 to £40; they were structurally excluded before.
Check the current rate schedule in Seller Central before enrolling - The actual programme fee percentage is seller- and marketplace-specific and is not the same for every account.
Enrol individually, in bulk, or all eligible products in one pass - Pick the option that matches how many newly-eligible SKUs are involved; changes go live to customers within 24 hours.
Watch for an Inactive status rather than treating it as a removal - A price drop below the minimum, an out-of-stock event or a suppression all cause this automatically, and it clears on its own once resolved.
Download the performance report from Manage enrolled products periodically - This is the one place to see how many orders are actually using the instalment option versus paying normally.
What SellerMagnet can and cannot do about this
Enrolling a product in Flexible Customer Financing, checking its eligibility status and reading the current rate schedule all happen inside Seller Central itself; no third-party tool, including SellerMagnet, enrols a product or sets the instalment terms on a seller's behalf. Where a margin check genuinely helps is before enrolling: the programme fee is charged on top of the referral and fulfilment fees a sale already carries, so confirming the full fee stack against the Fee Calculator for a newly-eligible £40 to £80 product avoids enrolling a thin-margin SKU into an extra per-transaction fee without first checking whether the margin can absorb it.
Once a product is enrolled, the real question is whether the instalment option is actually changing buying behaviour, not just whether it is turned on. The Manage enrolled products performance report inside Seller Central shows instalment-specific order counts, but comparing that against the SKU's overall conversion trend inside Analytics is what shows whether the newly-unlocked £40 to £80 band is converting better since enrollment, or whether the extra fee is being paid for no measurable lift.
What is Amazon's Flexible Customer Financing programme?
A programme that lets an eligible customer pay for a qualifying product in fixed monthly instalments at 0% APR, funded by one of Amazon's financial partners. The seller still receives the full net sale amount in a single disbursement and pays a per-transaction programme fee only when a customer actually uses the instalment option.
What is changing in the UK store from November 2026?
Three things: a new 36-month payment term is added alongside the existing 48-month tier; sellers already enrolled in 48 months become automatically eligible for 36 months too with no action needed; and the minimum qualifying order value drops from £80 to £40.
Do I need to do anything if I'm already enrolled in the 48-month tier?
No. Amazon states the eligible ASINs already in the programme become automatically eligible for the 36-month term as well, under the same fee structure, with no separate opt-in.
Does the lower £40 minimum enrol my products automatically?
No. The lower minimum only changes which products are eligible. A product still needs to be enrolled through the Eligible products tab (individually, in bulk, or all at once) before it shows an instalment option to customers.
Does the instalment fee affect my referral or fulfilment fees?
No. The programme fee is a separate, additional per-transaction fee charged only on orders that actually use the 0% APR instalment option. It does not change the referral fee, the fulfilment fee, or the net sale price of the order.
What happens if a customer misses an instalment payment to the lending partner?
Amazon's own help page states the seller's account is not affected. The financial partner carries that risk, not the seller.
Which products can never qualify for instalments, regardless of price?
Gift certificates, digital products such as ebooks, apps, games and software downloads, out-of-stock products, and services or warranties, per Amazon's own exclusion list.
Does the US store use the same £40/£80 figures?
No. The US programme page uses a $50 minimum order value and different term lengths (3, 6, 12, 18, 24 months or 8 bi-weekly payments). Each marketplace has its own minimum and term structure; check the matching help page for each store a listing sells in.
Stop Juggling Tools. SellerMagnet Combines Everything You Need.